Retirement planning often involves balancing multiple objectives. Many retirees seek income to support their lifestyle, flexibility to address changing needs, and strategies to help manage uncertainty over time.
While investment portfolios frequently play a central role in retirement income planning, some people also consider products designed to provide a level of income protection. These solutions, often referred to as protected income products, may serve a specific purpose within a broader retirement strategy.
Understanding how these products work, along with their potential benefits and limitations, can help retirees evaluate whether they align with their goals and circumstances.
What Are Protected Income Products?
Protected income products generally refer to financial solutions that may provide contractual income features or principal protection components, depending on the specific product and terms.
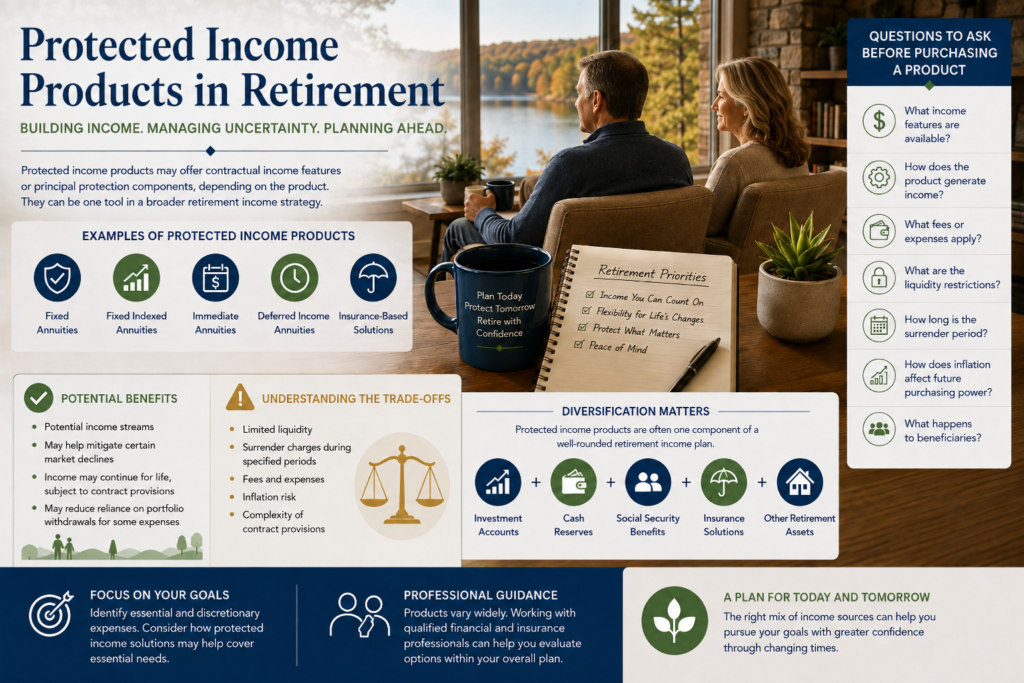
Examples may include:
- Fixed annuities
- Fixed indexed annuities
- Immediate annuities
- Deferred income annuities
- Certain insurance-based retirement income solutions
These products vary significantly in structure, costs, liquidity provisions, and income features. Reviewing the details carefully is important before making any decisions.
Why Some Retirees Consider Protected Income Strategies
One concern many retirees face is the possibility of outliving their financial resources.
Unlike a paycheck during working years, retirement often requires creating income from multiple sources, such as:
- Social Security1 benefits
- Retirement accounts
- Investment portfolios
- Pension income2, when available
Protected income products may be considered by individuals who want a portion of their retirement income strategy to rely on contractual features rather than market performance alone.
Potential Benefits to Consider
Depending on the product, protected income solutions may offer certain features that appeal to retirees.
These may include:
- Potential income streams
- Potential for mitigating certain market declines
- Income options that may continue for life, subject to contract provisions
- Reduced reliance on portfolio withdrawals for some expenses
For some individuals, these features may help support overall retirement income planning.
However, benefits vary significantly by product and carrier, and all contract provisions should be reviewed carefully.
Understanding the Trade-Offs
While protected income products may offer advantages in certain situations, they also involve trade-offs.
Potential considerations may include:
- Limited liquidity
- Surrender charges during specified periods
- Fees and expenses
- Inflation risk
- Complexity of contract provisions
For example, a product that provides income stability may offer less flexibility than other investment options. Understanding these trade-offs is an important part of evaluating suitability.
The Importance of Diversification
Protected income products are often considered one component of a broader retirement strategy rather than a complete solution.
Many retirees maintain a combination of:
- Investment accounts
- Cash reserves
- Social Security benefits
- Insurance solutions
- Other retirement assets
Diversifying income sources may provide flexibility when financial needs or market conditions change.
The appropriate mix depends on individual goals, risk tolerance, income needs, and overall financial circumstances.
Evaluating Income Needs
Before considering any retirement income product, it may be helpful to identify essential and discretionary expenses.
Examples of essential expenses may include:
- Housing costs
- Utilities
- Food
- Healthcare expenses
- Insurance premiums
Discretionary expenses may include travel, hobbies, gifts, and entertainment.
Some retirees explore protected income solutions as a way to help address a portion of their essential expenses while maintaining flexibility elsewhere in their financial plan.
Questions to Ask Before Purchasing a Product
When evaluating any protected income strategy, consider asking:
- What income features are available?
- How does the product generate income?
- What fees or expenses apply?
- What are the liquidity restrictions?
- How long is the surrender period?
- How does inflation affect future purchasing power?
- What happens to beneficiaries?
Understanding the answers to these questions can help provide greater clarity when comparing options.
The Value of Professional Guidance
Retirement income planning often involves balancing multiple factors, including taxes, investments, healthcare costs, longevity considerations, and estate planning goals.
Because protected income products vary significantly, reviewing options with qualified financial and insurance professionals can help individuals better understand how a particular product may fit within their broader strategy.
Careful evaluation is especially important because decisions involving retirement income often have long-term implications.
Building a Retirement Income Strategy
Protected income products can play a role in retirement planning for some individuals, but they are not appropriate for every situation.
By understanding the potential benefits, limitations, costs, and contractual features involved, retirees can make more informed decisions about how these solutions may fit within a comprehensive retirement strategy.
The goal is not simply to select a product, but to build a retirement income plan that aligns with your objectives, priorities, and evolving financial needs over time.
A thoughtful assessment can help create an investment strategy that aligns with personal goals while supporting informed decision-making through changing market environments.
Sources:
- [1] https://www.ssa.gov/
- [2] https://www.investopedia.com/terms/p/pensionplan.asp
Recent Posts
 Buckle Up: Why Markets Could Get Bumpy This Fall
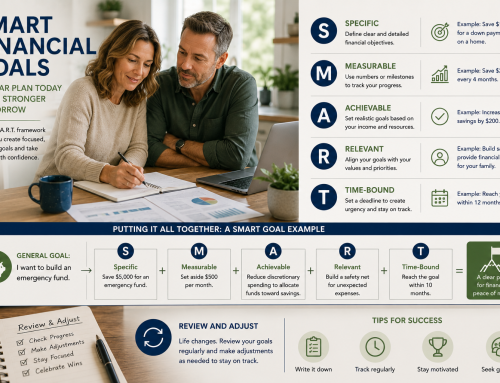
 Setting Effective Financial Goals for Sustainable Success
 Understanding Where Protected Income Strategies May Fit Within a Retirement Plan
 Charitable Giving Strategies: Planning Your Giving Before Year-End to Support Causes That Matter to You
 Taking a Proactive Approach to Important Financial Decisions Before Year-End
 This Charge Doesn’t Add Up
- Scam of the Month: One Letter Away from a Scam
 Tax Diversification in Retirement: Building Flexibility for Future Income Needs
 Understanding the Difference Between Risk Tolerance, Risk Capacity, and Financial Goals
 Back-to-Routine Money Reset: Taking Stock Before the End of the Year
- Scam of the Month: This Job Won’t Work
 Planning for Longevity: Preparing for a Retirement That May Last Decades
 Why Putting Your Financial Strategy in Writing Matters
 Summer Financial Checkup: Reviewing Your Progress and Priorities
- Scam of the Month: FIFA Phishing
 Israel Chavez, Jr. joined the ILG Financial team in 2026 as a Service Advisor. A graduate of Howard University, Israel was also a Division I student-athlete, competing as a goalkeeper for the university’s soccer program. His experience balancing academics and collegiate athletics helped shape the discipline and competitive mindset he brings to his role at ILG Financial.
 Megan Jones joined the ILG Financial team in 2020 as marketing director. Megan and her husband live in Fredericksburg, VA with their German Short Haired Pointer, Gus. Megan is a graduate of Longwood University and holds a degree in communications. Megan is the oldest of Dave Lopez’s three children and not only enjoys working alongside her father, but also with her cousin, Chase, who joined the ILG Financial team in 2020 as an advisor. Megan is also a fully licensed Life, Health, and Annuity agent. When not at work, Megan enjoys sitting on the back porch with family and friends enjoying food and music.
 Amy Anderson joined the ILG Financial team in 2023 as the client relations coordinator. Her responsibilities include scheduling of appointments, annual check-up notifications, and annuity and required minimum distribution assistance. She is a graduate of Harding University with a degree in Computer Information Systems. Amy and her husband have two children and she enjoys reading, crocheting, music and spending time with her family.
 Terri Center joined the ILG Financial team in 2019 as client services manager. She handles client records, application processing, and gathering information to provide a professional and friendly experience with all of our clients. Terri is a graduate of Oakland University. She is married and has two children. She enjoys hiking, family time, and puzzle challenging video games. She also likes to share her creativity in her canvas paintings and sewing projects.
 Jessica Carson joined the ILG Financial team in 2018 as an agent. Jessica and her husband have four children, two dogs, 3 barn cats, 5 chickens, and three parakeets. She indeed loves her children and pets! When not at work, Jessica enjoys playing the piano and cello as well as traveling and spending time outside with her family, hiking, fishing, and boating.